Realized and unrealized P&L need different price evidence
Realized P&L follows an executed closing transaction under the chosen accounting method.
Separate a completed exit from an open valuation
Realized P&L follows an executed closing transaction under the chosen accounting method. Unrealized P&L values an open position using a specified current mark. They answer different questions. An open-position estimate should identify the mark’s source and timestamp; it is not evidence that the position could be closed for that exact amount after all costs.
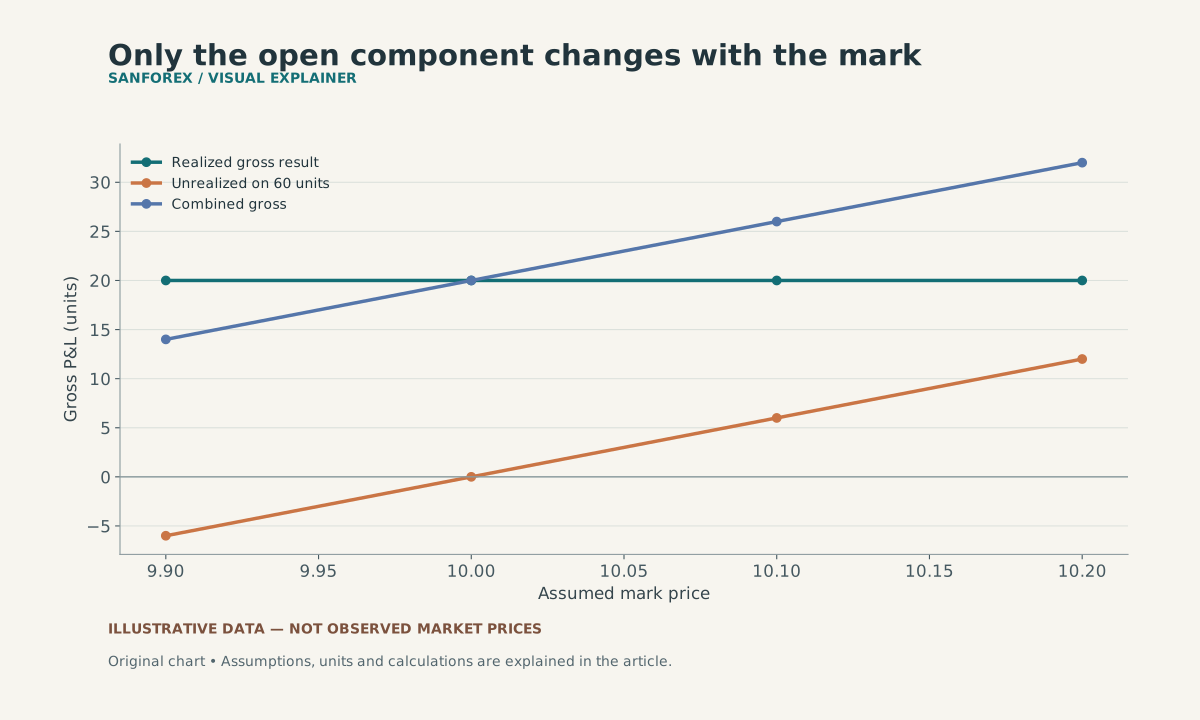
After 40 of 100 units exit at 10.50 from a 10.00 entry, realized gross profit is 20. The remaining 60 units change value with the stated mark. Costs and contract multipliers are excluded.
Open full-size diagram ↗Value a partially closed position
In a simple invented unit model, buy 100 units at 10.00 and sell 40 at 10.50. Realized gross profit is 40 × 0.50 = 20. Sixty units remain. At a mark of 10.20, their unrealized gross profit is 60 × 0.20 = 12. The combined gross result at that mark is 32, of which only 20 comes from the completed exit.
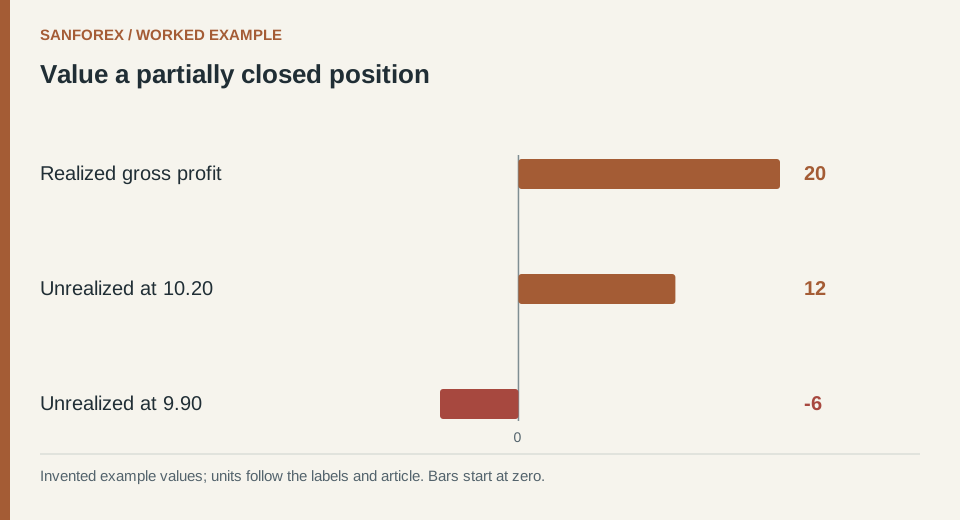
Worked example: Realized gross profit: 20; Unrealized at 10.20: 12; Unrealized at 9.90: -6. Invented values; units follow the row labels and article.
Open full-size diagram ↗Change the mark and observe what moves
If the mark changes to 9.90, unrealized P&L becomes minus 6 and combined gross P&L becomes 14. The already realized gross amount stays 20 in this example. Bid, ask, midpoint and last-trade marks can differ. Use the mark appropriate to the stated purpose and do not quietly compare reports built from different choices.
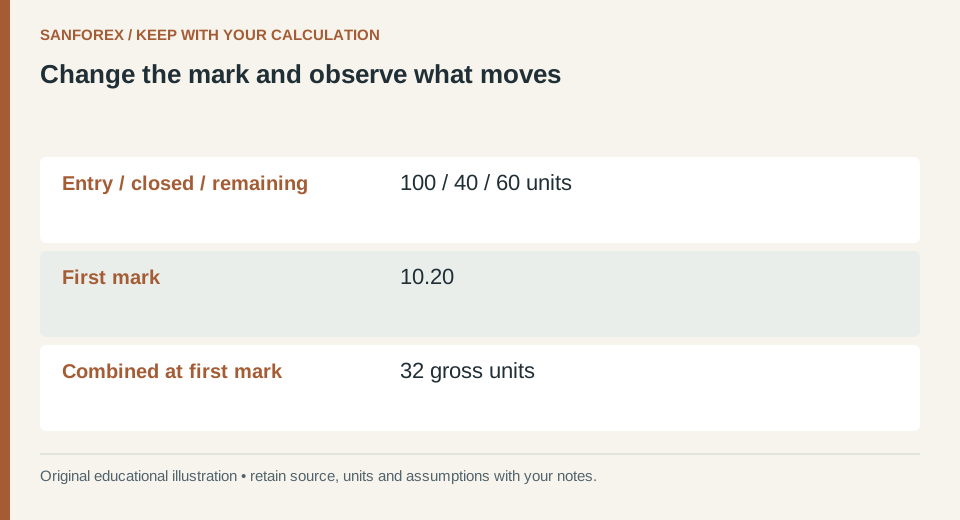
Calculation checklist: Entry / closed / remaining: 100 / 40 / 60 units; First mark: 10.20; Combined at first mark: 32 gross units. Preserve these definitions when reproducing the example.
Open full-size diagram ↗Reconcile costs and cash separately
Fees, financing, currency translation and settlement can change the relationship between these gross figures and an account’s cash movements. Keep them explicit rather than treating account balance as a synonym for total P&L. This illustration assumes no contract multiplier and no costs. A report should state those limitations and retain remaining quantity so the unrealized calculation can be reproduced.
Sources and conventions
Examples are hypothetical. Worked examples state their formulas and assumptions in the article; our methodology explains the related calculators. Broker contract specifications determine actual lot, margin and execution conditions. These sources document definitions and data; a source link does not imply endorsement of SanForex or a trading service.
These materials are prepared with AI assistance and checked against worked examples and deterministic calculation tests where applicable. They are not an expert suitability assessment or investment advice.
Open trading journal tool ↗